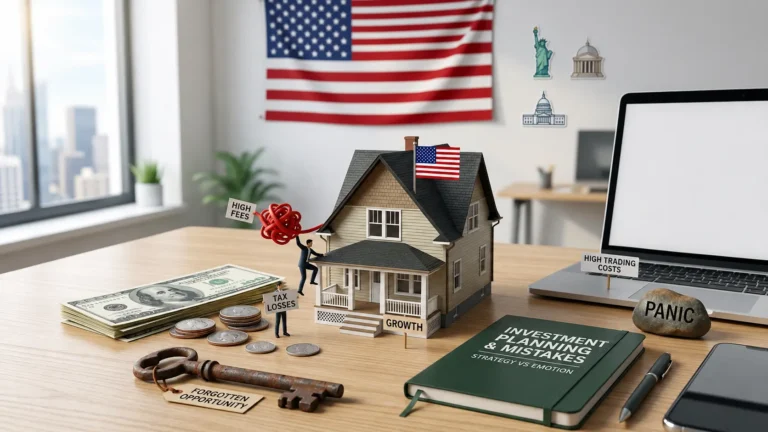
Building long-term financial security requires more than just picking the right assets; it demands a deep understanding of psychological discipline and risk management. Many individuals enter the financial market with grand ambitions, hoping to multiply their savings and secure a comfortable future. However, even the most promising strategies can crumble when subtle behavioral traps and systemic missteps begin to erode capital over time. Achieving true compounding success with investments demands constant vigilance, precise execution, and an awareness of the silent destroyers of portfolio value.
The illusion of constant market timing
Trying to predict every peak and trough of financial markets is a tempting pursuit that frequently leads to disappointing returns. Many market participants believe they possess the foresight to exit before a downturn and re-enter right at the bottom. In reality, market movements are driven by an overwhelming web of global events, economic indicators, and collective human psychology, making precise forecasting virtually impossible. Attempting to dance in and out of positions often results in missing the brief, explosive rally days that account for the vast majority of long-term gains.
When capital sits on the sidelines in cash while waiting for the perfect entry signal, inflation relentlessly chips away at its purchasing power. This hesitation creates a double penalty: lost opportunities for compound expansion and the silent erosion of real value. Moreover, the transaction costs, spreads, and tax obligations incurred from hyperactive trading rapidly accumulate, creating a heavy drag on overall performance. Successful historical strategies demonstrate that duration of exposure almost always outperforms the futile attempt to time entry points perfectly.
Sensationalist news headlines and market commentary often lure individuals into emotional decisions, prompting panic sales during sharp dips or desperate buying sprees at historical tops. This cycle of buying high out of fear of missing out and selling low out of sheer anxiety is the exact inverse of sound financial logic. Breaking free from this destructive loop requires accepting that short-term volatility is simply the price of admission for long-term real yield.
Establishing a consistent, automated contribution strategy helps neutralize the dangerous impulse to second-guess market momentum. By committing fixed sums at regular intervals regardless of temporary fluctuations, capital acquires more assets when prices drop and fewer when prices stretch thin. This disciplined framework removes the volatile element of human emotion from the equation, ensuring steady progress toward multi-decade objectives.
Ultimately, patience remains the most underappreciated virtue in wealth preservation and expansion. The compounding phenomenon needs adequate time to manifest its exponential magic, and constant interference disrupts this intricate process. By shifting focus away from short-term noise and honoring a well-constructed timeline, capital finds the quiet space it needs to flourish organically.
Overlooking the subtle weight of structural fees
Financial products often come wrapped in complex fee structures that appear negligible on paper but act as massive anchors over prolonged horizons. Management expenses, administrative surcharges, and performance fees silently eat away at compounding engine momentum long before returns reach the final balance sheet. A single percentage point paid annually to an intermediary might seem insignificant during strong bull markets, yet across thirty years, that tiny friction can consume up to a third of total potential gains.
Many individuals focus entirely on headline yields while completely ignoring the underlying expense ratios associated with actively managed funds or advisory services. Passive index structures and low-cost exchange-traded products have repeatedly demonstrated the ability to match or exceed active benchmarks simply by eliminating unnecessary layers of middleman compensation. Auditing every financial vehicle for hidden costs is an essential exercise for anyone serious about preserving their net worth growth trajectory.
Tax inefficiencies represent another major leak that drains wealth without providing any counter-balancing benefit. Failing to utilize tax-advantaged accounts, neglecting tax-loss harvesting opportunities, or triggering short-term capital gains levies through excessive turnover reduces the net proceeds available for reinvestment. Smart structuring ensures that a larger portion of generated returns remains within the portfolio to drive future expanding cycles.
Furthermore, trading spreads and currency conversion fees can quietly strip away gains, especially for international asset allocations. Ignoring these frictional mechanics means agreeing to an uphill struggle where assets must generate outsized returns just to break even against administrative drag. Minimizing operational expenses is one of the very few variables completely within an individual’s personal control.
Taking time to dissect contractual fine print and selecting lean, transparent modern platforms transforms passive leakages into active long-term advantages. Every dollar saved on unnecessary operational friction stays deployed in productive market mechanisms, multiplying silently across the decades. Vigilance regarding costs is not about being frugal; it is about protecting the fundamental mechanics of geometric progression.
Falling into the trap of narrow concentration
Concentrating assets into a tiny hand-full of popular equities or a single specialized sector creates a fragile foundation vulnerable to sudden shocks. While concentrated bets can occasionally yield spectacular short-term windfalls, they expose capital to unrecoverable losses if an unforeseen disruption hits that specific domain. Regulatory shifts, technological obsolescence, management scandals, or sudden geopolitical shifts can ruin even the most dominant industry leaders overnight.
True protection comes from building a resilient system capable of surviving a wide spectrum of economic weather conditions. A properly distributed balance sheet spans multiple geographic regions, asset classes, corporate sizes, and economic sectors, ensuring that a collapse in one area does not bring down the entire system. Diversification is not about maximizing returns in a single golden year; it is about guaranteeing survival across decades of unpredictable market shifts.
Many people fall victim to home bias, placing an excessive proportion of their resources into companies operating solely within their domestic borders. This geographic insularity leaves their financial health overly dependent on local regulatory environments, currency fluctuations, and domestic demographic trends. Incorporating international exposure provides a crucial shock absorber against regional recessions and currency devaluations.
Another common form of concentration risk occurs when individuals own substantial equity in the very company that pays their monthly salary. If that enterprise experiences financial distress, the person risks losing both their primary income stream and a massive chunk of their accumulated net worth simultaneously. Decoupling personal labor earnings from asset allocation protects domestic stability during broader corporate downturns.
Expanding exposure across uncorrelated instruments allows different parts of the balance sheet to take turns driving overall progress. When riskier equities experience temporary setbacks, defensive holdings like sovereign bonds or tangible assets help stabilize overall portfolio value. This structural equilibrium keeps anxiety low and prevents the desperate, reactive decision-making that ruins financial futures.
Succumbing to emotional bias and herd behavior
Human psychology evolved to seek safety in crowds and react instantly to immediate threats, traits that serve survival well but sabotage modern wealth preservation. When financial markets experience irrational exuberance, the fear of missing out drives people to abandon prudent risk parameters and buy overvalued assets near their peak. Conversely, when economic pessimism takes hold, the natural urge to flee prompts individuals to liquidate quality assets at steep discounts.
Anchoring bias frequently prevents people from cutting losses on deteriorating positions simply because they are fixated on the original price paid. Holding onto failing endeavors in the faint hope of breaking even keeps capital trapped in stagnant or declining assets when it could be working far more productively elsewhere. Acknowledging a mistake and reallocating resources to higher-conviction opportunities is a signature mark of mature capital management.
Confirmation bias leads individuals to selectively consume news and commentary that validates their existing positions while ignoring clear warning signs. This echo-chamber effect blinds people to shifting macro trends, disruptive competitive threats, and structural deteriorations in their holdings. Maintaining an objective, skeptical perspective requires actively seeking out counter-arguments to one’s own financial hypotheses.
Recent performance bias causes people to project current market conditions indefinitely into the future, assuming bull markets will last forever or recessions will never end. This short-sighted view leads to poor asset allocation decisions, such as taking on excessive debt during expansions or hoarding cash during the early stages of recovery. Developing a historical perspective helps ground expectations in reality rather than recent excitement or dread.
Overcoming these deeply ingrained mental shortcuts demands strict reliance on objective, rules-based frameworks rather than gut feelings. Documenting an asset allocation policy, defining clear rebalancing thresholds, and establishing pre-planned entry and exit guidelines removes emotional volatility from execution. Disciplined processes will consistently triumph over unguided intuition in the complex world of capital allocation.
Neglecting periodic rebalancing and continuous education
A static approach to managing wealth almost always leads to unintended risk exposure over time as different asset classes grow at varying rates. During extended economic expansions, high-risk growth assets naturally outpace conservative fixed-income holdings, causing the overall risk profile to expand far beyond original intentions. Without systemic recalibration, a portfolio designed for balanced growth can quietly mutate into a high-volatility vehicle right before a severe market contraction.
Periodic rebalancing forces the disciplined practice of trimming assets that have surged in value and redeploying those gains into areas that are currently undervalued. This methodical process systematically enforces the golden rule of wealth management—buying low and selling high—without relying on subjective market forecasts. Establishing set calendar intervals or clear percentage thresholds ensures that risk exposure remains strictly aligned with long-term tolerance levels.
In parallel with structural maintenance, failing to stay informed about evolving global economics, tax legislation, and technological shifts leaves wealth vulnerable to unexpected disruptions. The tools, platforms, and asset structures available today differ vastly from those of past decades, offering lower costs and broader access to global markets. Remaining stagnant in one’s knowledge base means missing out on modern efficiencies that can meaningfully optimize risk-adjusted returns.
However, continuous education should not be confused with consuming daily market commentary or reacting to fleeting social media financial trends. True educational growth involves studying economic history, understanding fundamental principles of valuation, and mastering the behavioral patterns that drive long-term capital cycles. Building a deep intellectual foundation allows individuals to discern enduring structural shifts from temporary speculative manias.
Ultimately, managing capital is a lifelong journey of continuous learning, self-control, and mechanical optimization. Treating wealth management as a dynamic practice that requires regular maintenance and informed oversight ensures that long-term goals remain firmly within reach. By avoiding common behavioral pitfalls, controlling operational costs, and maintaining structural discipline, individuals can unleash the full power of compounding and build lasting financial freedom.